The Blog
Profit Insights™️
Strategy, frameworks, and field notes on turning revenue into profit — for real estate professionals and service-based CEOs.
Real Estate Finance · 14 min read
Q4 Is the Quarter That Makes or Breaks Real Estate Cash Flow: A Year-End Countdown for Agents, Brokers & Investors
By Erika Jones — Founder & Fractional CFO, She Knows Profits™
Q4 is not simply the final quarter of the year. It is your last strategic window to influence how much cash you keep, how much tax you owe, and how confidently you enter 2027.
For real estate professionals, this matters more than it does for many other business owners. Commission income is uneven. Closings can move without warning. Property repairs can become capital expenditures. A strong month can create a tax obligation months later. One poorly timed purchase can drain liquidity while producing little strategic value.
The question is not, “How do I spend money before December 31?”
The better question is: Which decisions will strengthen profitability, protect cash, and support the next stage of my business?
Here is your Q4 cash flow countdown.
Field Note: Q4 Decisions Affect More Than Taxes
Tax planning and cash flow planning are connected—but they are not the same.
A deduction may reduce taxable income. It does not automatically improve your bank balance. Buying a vehicle you do not need, prepaying expenses without a plan, or accelerating a property improvement can leave you with less cash and more financial pressure.
Your Q4 strategy should evaluate three outcomes:
- Tax impact: How will the decision affect taxable income?
- Cash impact: When does the money leave the business?
- Strategic impact: Does the decision improve capacity, profitability, or wealth?
That is the standard Erika Jones uses when helping real estate professionals build proactive financial systems through the She Knows Profits™ Tax Advisory service.
Now Through September 15: Establish the Baseline
The first Q4 move is not a purchase. It is a current-year financial review.
Pull together:
- Year-to-date revenue by business or entity
- Commissions earned, received, and still outstanding
- Pending closings and their realistic settlement dates
- Operating expenses and unusual one-time costs
- Tax reserves and estimated payments
- Property income, repairs, improvements, and debt service
- Owner distributions and personal draws
- Retirement contributions made so far
If you are self-employed, a partner, or an S-Corporation shareholder, the IRS generally expects taxes to be paid as income is earned. The September 15, 2026 estimated tax deadline is the next major checkpoint for many taxpayers. The January 15, 2027 payment generally covers the final estimated-tax period of 2026.
The IRS explains that taxpayers may generally avoid an underpayment penalty by paying at least 90% of current-year tax or 100% of prior-year tax, whichever is smaller—with special rules for certain higher-income taxpayers and uneven income patterns. Review the IRS estimated tax guidance and coordinate with your tax advisor.
Do not treat a tax reserve as available operating cash. Separate it. Label it. Protect it.
12 Weeks to Year-End: Review Commissions and Closing Timing
Real estate income rarely arrives in a smooth monthly pattern. That makes forecasting essential.
For agents and brokers
- Expected commissions from pending transactions
- Commission splits and brokerage fees
- Bonuses or team distributions
- Year-end marketing and lead-generation commitments
- Whether a closing is likely to occur in 2026 or 2027
For investors
- Planned property sales
- Rental income and lease timing
- Capital gains exposure
- Potential 1031 exchange considerations
- Property improvements that may be completed before year-end
- Whether a delayed closing creates a reserve problem
You should never manipulate a transaction date solely for tax reasons without considering legal, contractual, financing, and business consequences. But you should understand the timing. A closing that moves from December to January may shift income, estimated tax needs, debt service, and available cash into a different reporting period.
Model both scenarios before the decision becomes urgent.
10 Weeks to Year-End: Decide What to Buy—and What Not to Buy
Equipment, technology, furniture, vehicles, and office improvements often become Q4 conversation points.
The right question is not, “Can I deduct this?” Ask:
- Is the purchase necessary?
- Will it create measurable capacity or revenue?
- Can the business pay cash without weakening reserves?
- Does it qualify as a current expense, repair, or depreciable asset?
- When will it be placed in service?
- Will financing create a payment obligation that extends into a slower season?
Vehicle planning
A vehicle may be significant for real estate professionals who drive to listings, inspections, showings, closings, and investor meetings. Your year-end review should include:
- Complete business-mileage records
- Business versus personal use
- Standard mileage versus actual-expense analysis
- Purchase versus lease considerations
- Insurance, maintenance, and financing costs
- Whether the vehicle is genuinely needed for the business
A vehicle purchase can create a tax deduction, but it can also create debt, depreciation, insurance, and maintenance obligations. Run the full cash-flow model before signing.
Repairs versus improvements
A repair and an improvement may not receive the same tax treatment. Routine repairs may be treated differently from renovations or improvements that extend useful life, increase value, or adapt a property to a new use.
Investors should document the work, invoices, completion dates, and property purpose. Some qualifying assets may benefit from accelerated depreciation under current law, but the result depends on the asset, placed-in-service date, ownership structure, and your overall tax position.
Tax law changes. Confirm the treatment with your tax advisor before committing capital.
8 Weeks to Year-End: Evaluate Retirement Contributions
Retirement contributions can support both long-term wealth creation and tax planning. For self-employed realtors, brokers, and investors, Q4 is the time to estimate full-year income and determine whether a retirement contribution fits the broader plan.
- Current-year net income
- Existing retirement contributions
- Available plan options
- Contribution deadlines
- Employer or employee contribution components
- Cash required for taxes and operating reserves
Do not make a large contribution simply because you want a deduction. Coordinate the contribution with estimated taxes, owner pay, reserve requirements, and near-term business needs.
A contribution that supports your wealth strategy is different from a contribution that creates a January cash crunch.
6 Weeks to Year-End: Review Your Entity and S-Corporation Strategy
Entity structure should be reviewed before Q4 closes—not after tax filing begins.
For eligible business owners, an S-Corporation election or S-Corporation compensation strategy may affect payroll, distributions, compliance, and tax planning. It also creates administrative obligations, including reasonable compensation, payroll processing, filings, and clean bookkeeping.
- Whether your current entity still fits your income level and risk profile
- Owner compensation
- Payroll compliance
- Distributions
- State tax implications
- Retirement plan coordination
- Whether an election or restructuring is still available for the current tax year
An S-Corporation is not a universal tax solution. It is a structure that must be modeled and managed correctly.
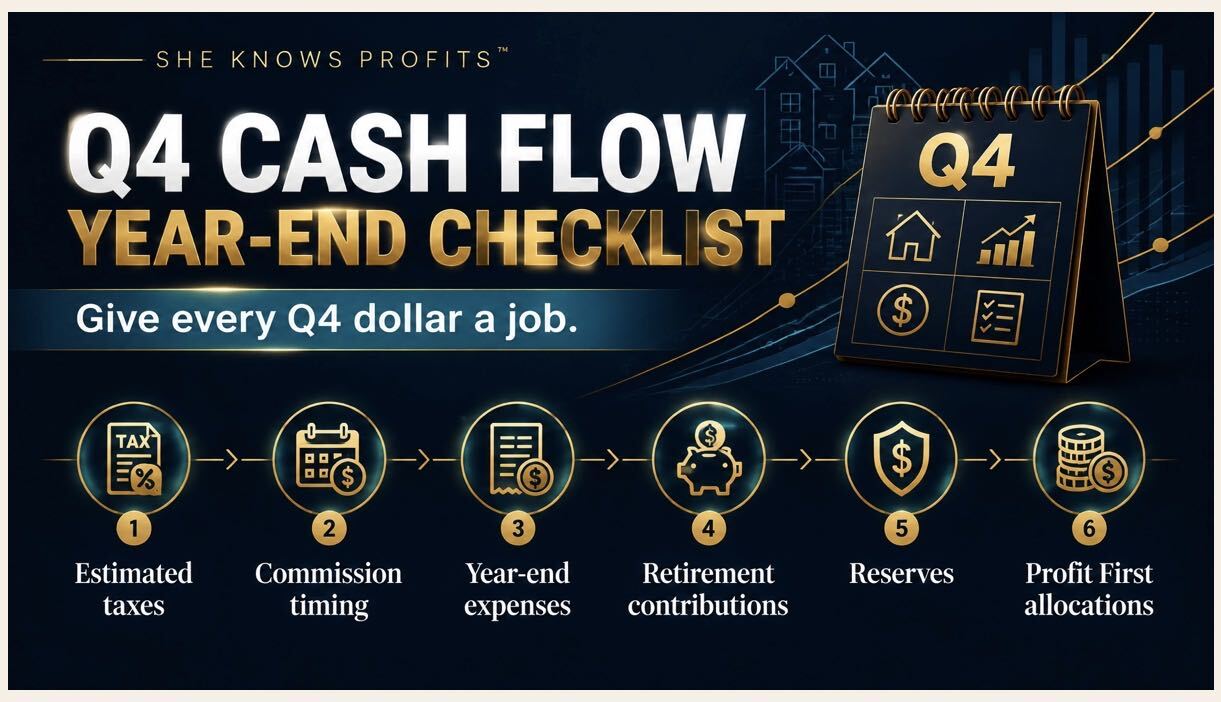
4 Weeks to Year-End: Complete Your Profit First Allocation Check
Uneven income requires a system that prevents strong commission months from creating weak quarters.
Before December 31, review your allocation accounts:
- Profit
- Owner’s compensation
- Tax
- Operating expenses
- Reserves
Compare your actual allocations with your target percentages. If operating expenses consistently consume every commission, the issue may be pricing, staffing, subscriptions, debt, or spending behavior—not simply revenue.
Use Q4 to identify the gap between what your business earns and what it retains. The Profit First for Real Estate Investors guide offers additional context for creating intentional cash allocation.
2 Weeks to Year-End: Protect Reserves and Make Debt Decisions
Before the final closing of the year, stress-test your cash position. Calculate your ability to cover:
- Taxes due January 15
- Payroll and contractor obligations
- Debt payments
- Insurance renewals
- Property repairs
- January operating expenses
- Slower-than-expected Q1 revenue
Then review debt decisions. Refinancing, paying down debt, taking on new financing, or using a business credit line may each have different effects on liquidity and profitability.
Debt is not automatically bad. Unstructured debt is expensive. Make the decision based on return on capital, repayment capacity, and the role the debt plays in your long-term plan.
The She Knows Profits™ Cash Flow Advisory service helps business owners build reserves, monitor allocations, and create a more predictable cash rhythm.
December 31: Close the Loop
Before the year closes, confirm:
- Books are current
- Outstanding invoices are identified
- Commissions and closings are reconciled
- Estimated tax payments are scheduled
- Tax reserves are separated
- Mileage and expense records are complete
- Asset purchases are documented
- Property repairs and improvements are classified for review
- Retirement contributions are coordinated
- Entity and S-Corporation questions are addressed
- Q1 cash needs are forecasted
This is the difference between reacting to last year’s numbers and leading the next year with sharper thinking.
A Fractional CFO partnership can add the forecasting, reporting, decision support, and accountability required when your business has outgrown basic bookkeeping.
Frequently Asked Questions About Q4 Real Estate Cash Flow Planning
What should realtors do before the end of the year?
Realtors should review commissions, estimated taxes, owner compensation, mileage records, vehicle plans, retirement contributions, operating expenses, and cash reserves. The goal is not to create artificial deductions—it is to make informed decisions that support profitability and liquidity.
When are the Q4 estimated taxes due?
For many individual taxpayers, the final estimated tax payment for the 2026 tax year is due January 15, 2027. The September 15, 2026 payment is also a key deadline. Your actual requirements may vary based on income, entity structure, withholding, state rules, and payment history.
Should I buy equipment or a vehicle before December 31?
Only if the purchase is operationally necessary, financially sustainable, and appropriately documented. A deduction does not make an unprofitable purchase profitable.
Should real estate investors harvest tax losses?
Tax-loss harvesting may be relevant when an investor has gains to offset, but the strategy requires careful analysis of basis, holding period, related-party rules, depreciation recapture, and investment objectives. Discuss the decision with qualified tax and investment professionals.
Does an S-Corporation automatically reduce taxes?
No. Potential savings depend on income, compensation, payroll costs, compliance, state taxation, retirement planning, and the owner’s broader financial picture. The structure must be modeled before implementation.
Build Your Financial Operating System Before Q4 Builds It for You
Q4 rewards preparation. Real estate professionals who forecast commissions, protect reserves, plan estimated taxes, and evaluate major decisions early enter the new year with options—not pressure.
Erika Jones, Founder of She Knows Profits™, Fractional CFO, Certified Tax Advisor, and Advanced Certified Profit First Professional, helps real estate professionals turn revenue into structured cash flow, stronger profitability, and long-term wealth.
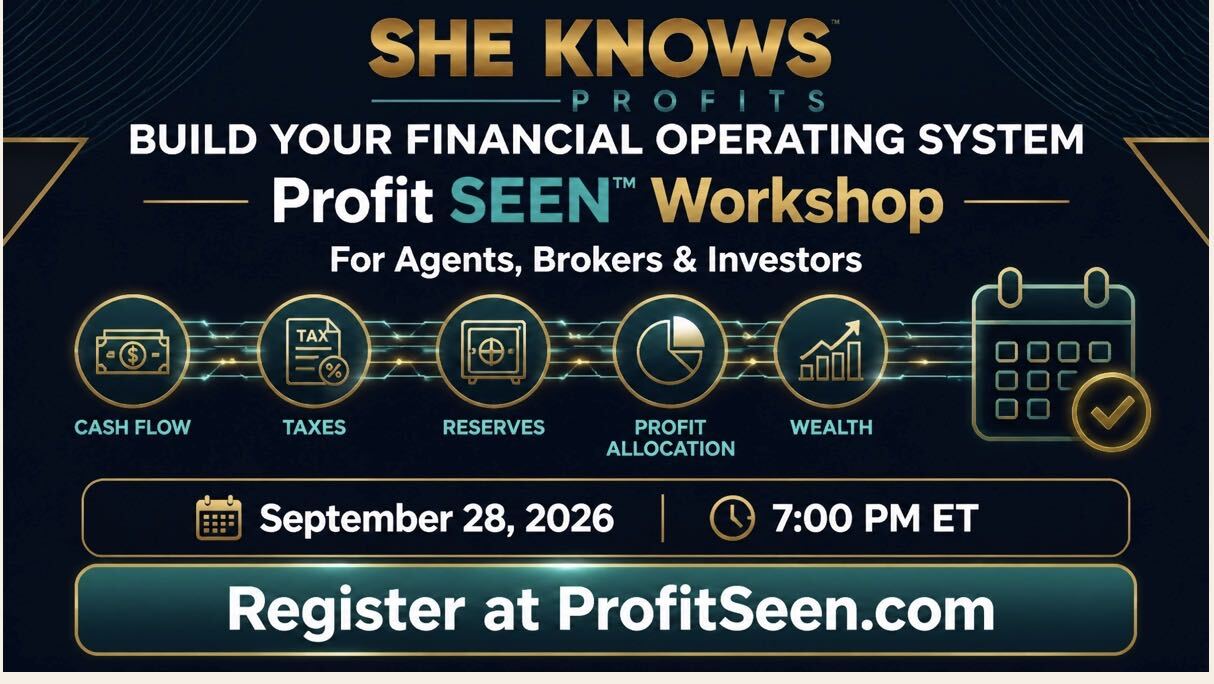
Join Erika for the Profit SEEN™ Financial Operating System Workshop beginning September 28, 2026, at 7:00 PM ET. The three-day implementation experience covers cash flow visibility, profit allocation, tax strategy, forecasting, and wealth-building systems.
Your next commission should not determine whether your business feels stable. Build the system that makes stability repeatable.
This article is for educational purposes only and is not individualized tax, legal, accounting, investment, or financial advice. Tax rules and deadlines may change. Consult your qualified advisors before making business, tax, investment, entity, or property decisions.
Q4 Is the Quarter That Makes or Breaks Real Estate Cash Flow: A Year-End Countdown for Agents, Brokers & Investors
From commissions and closings to tax reserves and property decisions, Q4 is where real estate professionals convert income into control.
Read ArticleProfit First for Real Estate Investors: Deposits, CapEx, and Owner Pay
Standard Profit First percentages break on a rental portfolio. Here's the six-account stack that separates tenant deposits, tax escrow, and per-door CapEx reserves from money you can actually spend.
Read ArticleThe 3 Financial Systems Every $500K+ CEO Needs Before They Can Scale
A rolling 13-week cash flow forecast, a proactive tax & profit planning engine, and monthly management accounts — the infrastructure that separates scaling CEOs from stalled ones.
Read ArticleLagging Indicators vs. Leading Indicators
Bank balance is yesterday's news. Here's the proactive CEO financial system — 13-week rolling forecast, weekly cash scorecard, and Profit First reserves — that $10M+ operators use to drive decisions.
Read ArticleThe Bank Balance Trap: Why Cash in Bank Is a Lagging Indicator for Growth
Managing by bank balance is like flying by looking at the smoke trail behind you. Here's how $10M+ CEOs replace reactive monitoring with a proactive CFO financial system.
Read ArticleThe CFO Role Just Expanded — But Nobody Trained the Team Beneath Them
93% of CFOs say their role now extends into enterprise strategy — yet 55% of junior finance pros say they aren't developing the skills they'll need next. That's a structural gap, not a talent one.
Read on LinkedInYour Engagement Spend Isn't Fixing Attrition
Organizations are spending thousands on engagement initiatives — yet their best employees are still leaving. Engagement and retention are not the same thing. People don't leave because they're unhappy; they leave because they can't see a future.
Read on LinkedInDebt Isn't the Problem — Mismanaged Debt Is
Debt itself isn't the enemy of a profitable business. Mismanaged debt is. The CEOs who scale are the ones who learn to structure it, time it, and put it to work.
Read on LinkedInYou Don't Need to Fire Your CPA — You Need a Tax Strategy
Most CEOs don't have a CPA problem. They have a strategy problem. Compliance keeps you legal; strategy keeps you profitable. The two roles are not the same.
Read on LinkedInBanks Don't Fund Hustle — They Fund Structure
Lenders don't get excited about revenue stories. They fund clean books, predictable cash flow, and a financial structure that proves you can repay.
Read on LinkedInAI Isn't the Risk — Running Your Business Without Cash Flow Is
Everyone is worried about AI disrupting their industry. The bigger risk for most CEOs is still the same one it's always been: running the company without a real cash flow system.
Read on LinkedInThe Day a Client Wasn't Afraid of Her Tax Bill
There's a moment in a CEO's life when the tax bill stops being scary. It happens when planning replaces reaction — and the number on the return is the number she already decided on.
Read on LinkedInThe Two-Week Window That Quietly Determines How 2026 Will Go
The decisions you make in the last two weeks of the year quietly set the ceiling for the next one. Most CEOs miss them because they're focused on closing — not on positioning.
Read on LinkedInWhy CEOs Don't Need More Reports — They Need a CFO Who Can Read the Story
More dashboards won't fix a decision problem. CEOs don't need more reports — they need a CFO who can translate the numbers into the story behind the business.
Read on LinkedInThe QBI Deduction Is Permanent — The Profit Lever Most CEOs Still Miss
The QBI deduction is now permanent — and it's still one of the most overlooked profit levers on the books. Used right, it changes how you draw, structure, and pay yourself.
Read on LinkedInHow to Use 100% Write-Offs to Immediately Boost Cash Flow and Keep More Profit
100% bonus depreciation is back. Used strategically, it doesn't just reduce taxes — it puts cash back into the business this year, on purpose.
Read on LinkedInProfit Hacks You're Probably Missing — How the One Big Beautiful Bill Changes the Game
The One Big Beautiful Bill rewrote the playbook on deductions, depreciation, and entity strategy. Most CEOs are still operating on last year's rules.
Read on LinkedInThe One Big Beautiful Bill — Why CEOs Should Pay Attention to the Fine Print
The headlines are loud. The fine print is louder. Here's what every CEO needs to understand about the One Big Beautiful Bill before they plan next year's profit.
Read on LinkedInWhy CFOs Can't Afford to Wait — Tariffs, Inflation & the Urgency of Profit
Tariffs, inflation, and tightening margins aren't a forecast — they're already here. CFOs who wait to react are giving up profit they can't get back.
Read on LinkedInRecession-Proof Is the New Rich — Why Smart CEOs Don't Wait to Feel It
Recession-proof is the new rich. The CEOs who win the next cycle aren't the ones reacting to it — they're the ones who built for it before it arrived.
Read on LinkedInComing Soon
LinkedIn articles, auto-published here.
Erika's LinkedIn articles will automatically repost to Profit Insights™️ for added SEO reach — one publish, two audiences.
Ready to build a financially healthy legacy?
Schedule a discovery call to discuss your tax strategy or CFO needs.
Book a Consultation